What can be corrected online on TRACES
| Correction type | Typical mistake | Effect if not corrected |
|---|---|---|
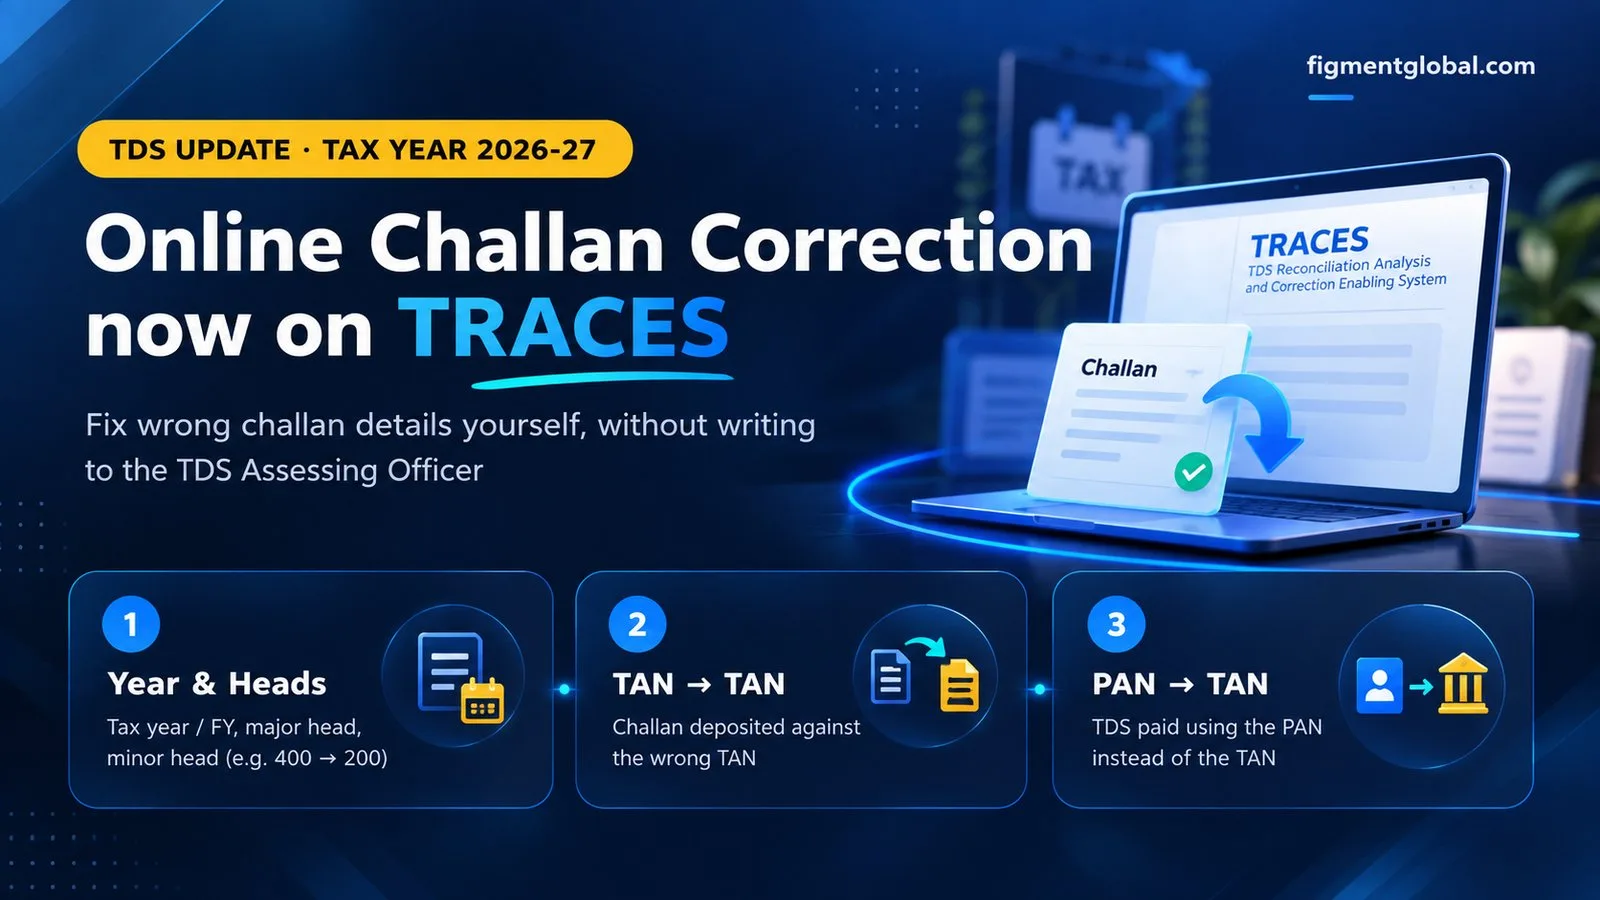
| Tax year / financial year, major head, minor head | TDS paid under minor head 400 (demand payable) instead of 200 (TDS payable by taxpayer), wrong major head, or wrong year | Challan cannot be matched in the TDS statement, showing short payment |
| TAN to TAN | Challan deposited against the wrong TAN, such as another branch or group entity, or a typo | Credit sits in another TAN; the correct TAN shows a default |
| PAN to TAN | TDS deposited using the PAN instead of the TAN | Amount cannot be used in any TDS statement until corrected |
Why this matters for deductors and CA firms
Tax Year 2026-27 vs earlier financial years
Challans for Tax Year 2026-27: use the challan correction facility on the main TRACES portal Challans for FY 2025-26 and earlier years: go to the "Compliance under the Income-tax Act, 1961" section on TRACES
List the challans with errors
Check the TRACES default summary and the challan status for unmatched or unconsumed challans, and note the BSR code, date, serial number and amount of each. Log in to TRACES as a deductor
Use the challan correction option for Tax Year 2026-27, or the Compliance under the Income-tax Act, 1961 section for FY 2025-26 and earlier. Submit the correction request
Select the correction type (year/head, TAN to TAN, or PAN to TAN), enter the challan details and the corrected values, and submit. Track the request
Follow the request status on TRACES until the correction is accepted. File a correction statement if needed
Once the challan shows the correct details, tag it to the right statement through a correction statement so the short payment default is removed. Software such as TaxCPC can prepare the correction statement.
Check before you correct
Frequently Asked Questions
Yes. TRACES has made online challan correction available for Tax Year 2026-27. For earlier years, up to FY 2025-26, deductors can use the Compliance under the Income-tax Act, 1961 section on TRACES.
Yes. The online facility covers corrections to the tax year or financial year, major head and minor head of a challan, so a challan paid under minor head 400 by mistake can be corrected to 200.
Yes. TAN to TAN correction is available online, so a challan deposited against the wrong TAN can be moved to the correct one.
The PAN to TAN correction lets you move a challan paid under the PAN to the correct TAN, so it can be used in the TDS statement.
If the TDS statement was already filed with a short payment, file a correction statement after the challan is corrected so the challan is matched and the default is removed.