

MSME Form 1 Due 31 October 2026: Filing Checklist for April–September 2026
Quick answer:
Who must file
Due dates
| Half-year | Due date |
|---|---|
| 1 April – 30 September 2026 | 31 October 2026 |
| 1 October 2026 – 31 March 2027 | 30 April 2027 |
What to report
supplier name and PAN; payments made within 45 days, including payments through TReDS or other modes; payments made after 45 days; amounts outstanding for 45 days or less; amounts outstanding for more than 45 days; and the reason for the delay in payment or amount outstanding.
Filing checklist
Confirm which vendors currently qualify as Micro or Small Enterprises
Start from a verified vendor list rather than relying only on the MSME flag captured at onboarding. A supplier's MSME classification can change over time based on the applicable investment and turnover criteria. Verify the current classification and Udyam status of relevant vendors before preparing the return. Pull every MSE invoice for April–September 2026
Include invoices raised before 1 April 2026 that were still unpaid on that date. Fix the acceptance date for each invoice
The 45-day period runs from the date of acceptance or deemed acceptance of the goods or services, not simply from the invoice date. Use supporting records such as GRNs, delivery records, service acceptance records or other documented evidence to establish the acceptance date. Flag every invoice paid after 45 days or still outstanding beyond 45 days
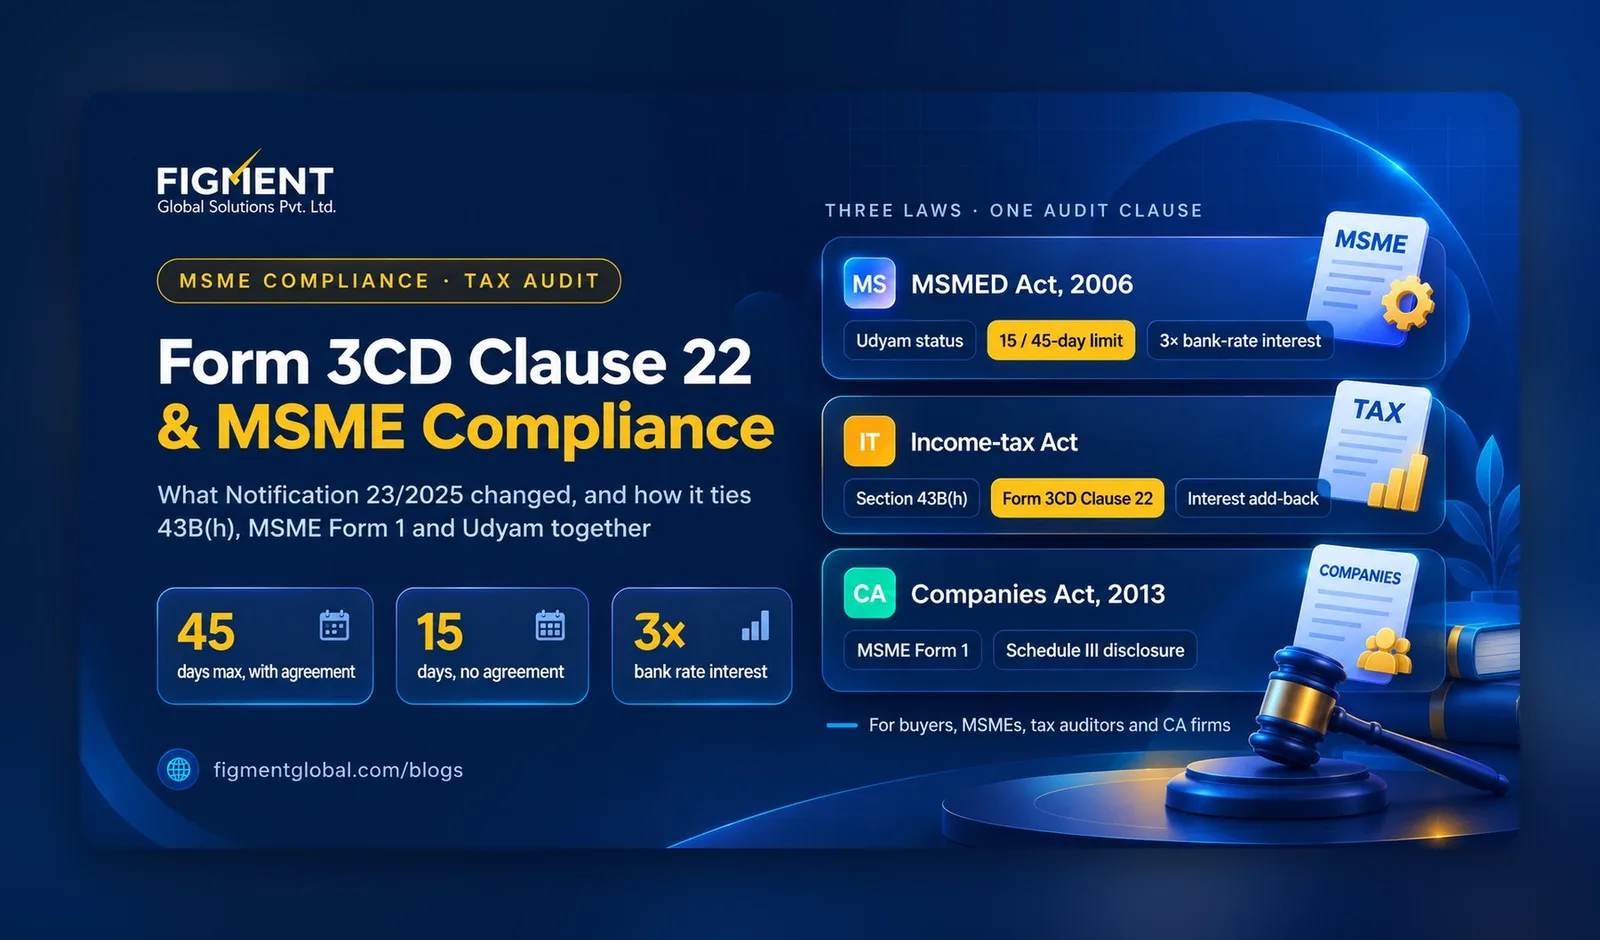
For MSME Form 1, identify payments that were made after 45 days as well as amounts that remain outstanding beyond 45 days. Separately, under the MSMED Act, where there is no written agreement, payment is generally required within 15 days; where there is a written agreement, the agreed payment period cannot exceed 45 days. Record the reason for each delay
Disputed quality, missing documents and pending approvals are common reasons. Keep the evidence. Reconcile before filing
Reconcile the Form 1 data with your accounts payable records and the applicable financial-statement and tax disclosures. The reporting requirements may differ across these records, so any differences should be explainable and supported by appropriate documentation. The MSMED (Amendment) Act, 2026 introduces graded penalties for certain Section 22 contraventions, subject to the commencement of the relevant provisions. File on the MCA V3 portal by 31 October 2026
MSME Form 1 is filed without a statutory filing fee. Submit the form electronically on the MCA V3 portal and digitally sign it through the authorised signatory specified in the form.
Penalty for Non-Filing or Incorrect/Incomplete Information
| Penalty | |
|---|---|
| Company | ₹20,000, plus ₹1,000 for every day the default continues, subject to a maximum of ₹3 lakh. |
| Each officer in default | ₹20,000, plus ₹1,000 for every day the default continues, subject to a maximum of ₹3 lakh. |
How Figment helps
Frequently Asked Questions
31 October 2026.
No. A company does not need to file MSME Form 1 merely because it has Micro or Small Enterprise suppliers. Filing is required when the company falls within the revised Form 1 reporting criteria, including relevant payments made after 45 days or amounts outstanding for more than 45 days.
No. Only micro and small enterprises are covered.
No. The form is filed free on the MCA portal.
Under Section 405(4), ₹20,000 plus ₹1,000 a day for continuing default, up to ₹3 lakh, for the company and for each officer in default.
No. MSME Form 1 applies to companies. LLPs must still pay MSE suppliers within the MSMED Act limit.
Yes. The revised MSME Form 1 requires reporting of amounts that were liquidated after 45 days, even if they were subsequently paid before the end of the half-year.