

Notification No. 03/2026–Central Tax brings Sections 153 to 155 of the Finance Act, 2026 into force. Section 155 amends Section 54 of the CGST Act. Notification No. 05/2026–Central Tax, the CGST (Amendment) Rules, 2026, rewrites Rules 89 to 92, the core refund rules.
The changes at a glance
| Area | Earlier position | From 1 November 2026 |
|---|---|---|
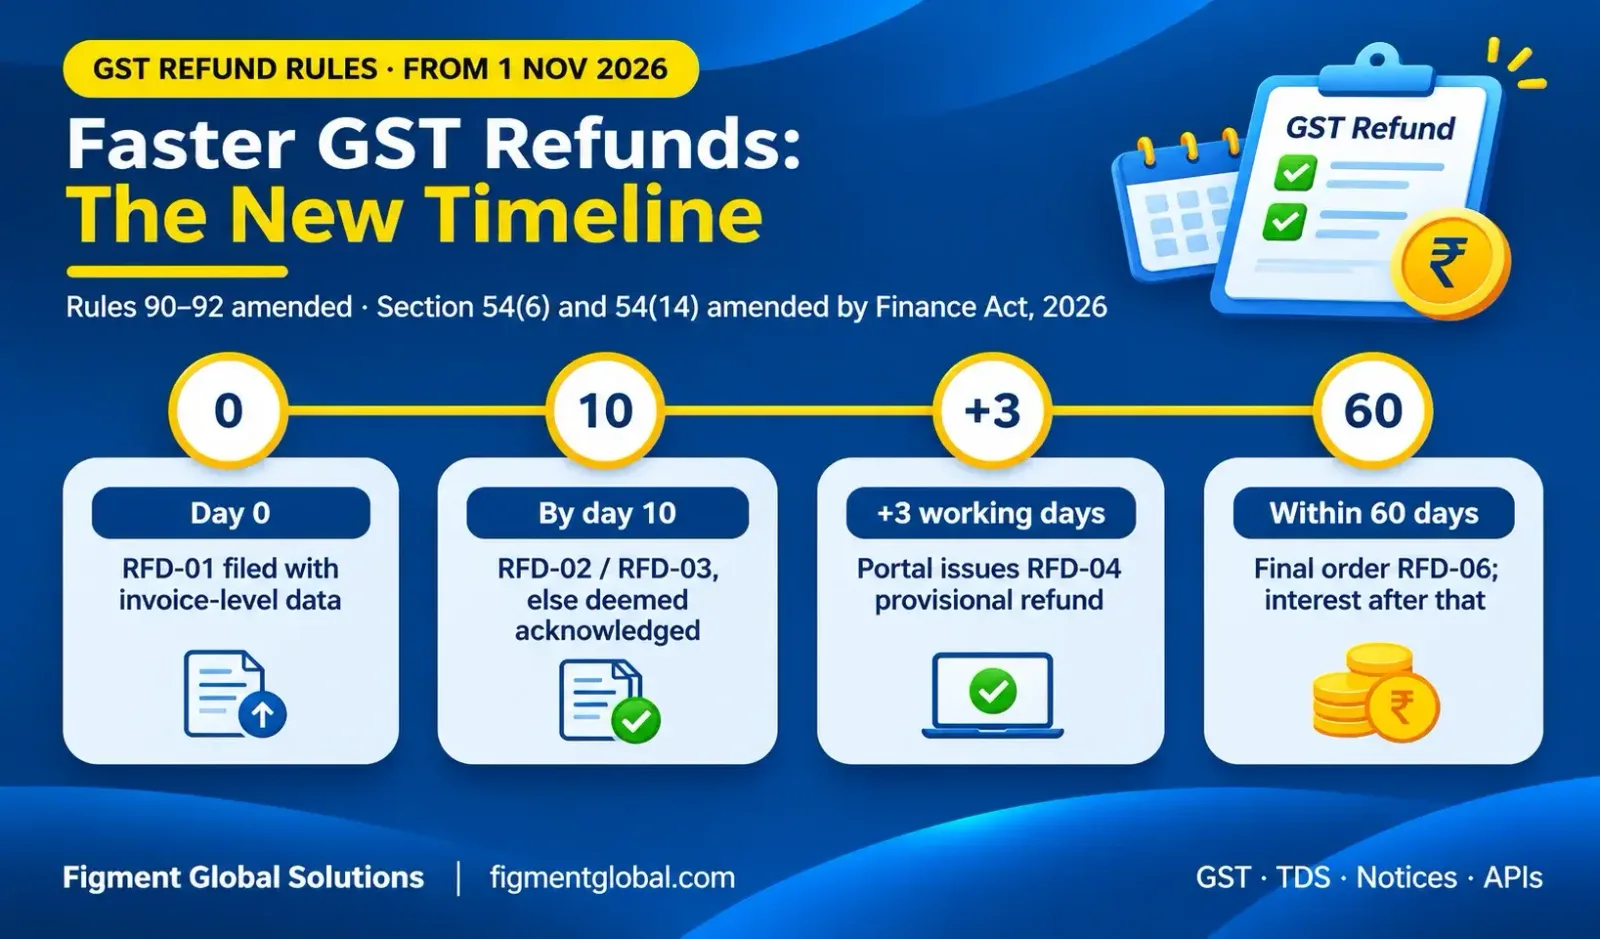
1. Acknowledgement in 10 days, or deemed
issue an acknowledgement in FORM GST RFD-02, or issue a deficiency memo in FORM GST RFD-03.
2. Provisional refund generated by the portal
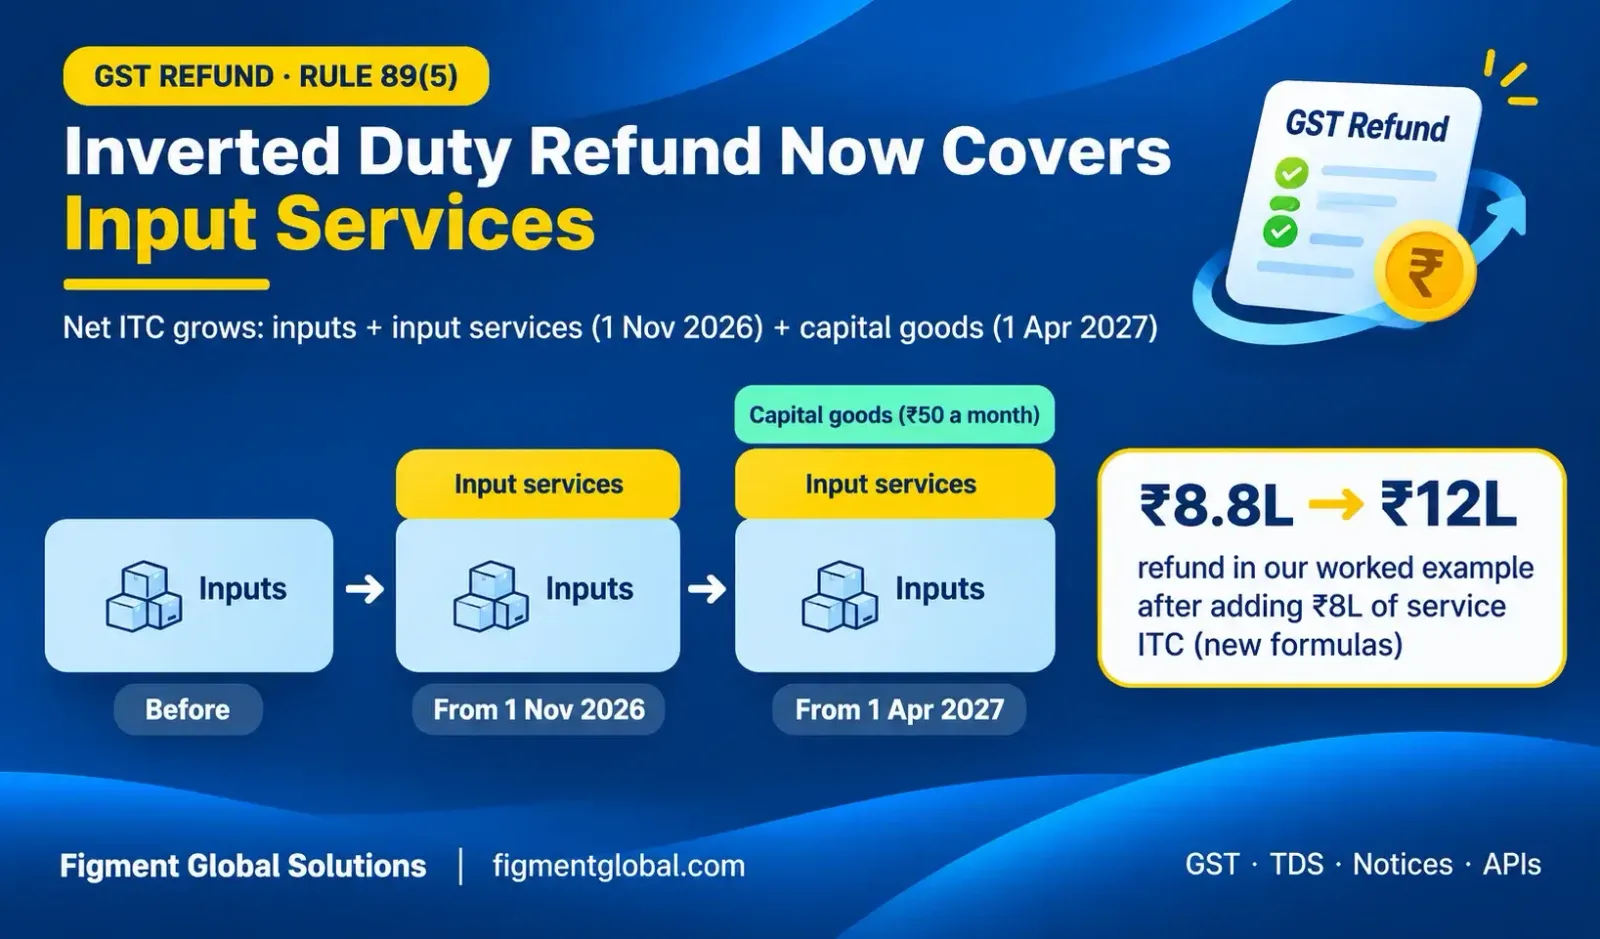
refunds on zero-rated supplies (exports and supplies to SEZ), and refunds of accumulated ITC due to an inverted duty structure.
Low-risk claims: the system issues the provisional refund without officer intervention. The claim then goes to the proper officer for final scrutiny and the final order. Other claims: the proper officer scrutinises the claim after acknowledgement and handles both provisional and final sanction.
3. Cash ledger refunds by the system
4. Exporters: 1.5x cap removed, small refunds paid
1.5x cap. Rule 89(4)(C) limited the value of zero-rated supply of goods to 1.5 times the value of like goods supplied domestically by the same or similarly placed supplier. That restriction is omitted from 1 November 2026, so exporters with premium pricing for overseas buyers no longer lose part of their refund to it. The notification does not separately say how claims covering supplies made before 1 November 2026 are to be treated; take advice before applying the removal to earlier supplies. ₹1,000 threshold. Section 54(14) blocked refunds below ₹1,000. Section 155 of the Finance Act, 2026 removes this restriction for goods exported on payment of tax, so small IGST refunds are now paid. The ₹1,000 limit still applies to other refund categories.
5. RFD-01 asks for more data
a statement of invoices with ITC details for claims of unutilised ITC, BRC/FIRC details for exports of services and shipping bill/EGM details for exports of goods, a statement linking invoices to shipping bills for merchant-exporter supplies, and a declaration about prosecution where tax evaded exceeds ₹250 lakh in the five years before the claim period.
The new refund timeline
| Day | Step |
|---|---|
Refund readiness checklist
Reconcile GSTR-1, GSTR-1A, GSTR-3B and GSTR-2B for the claim period before filing. From 1 December 2026, prepare invoice-wise statements in the new RFD-01 format. Exporters: match shipping bills, EGM, BRC/FIRC with invoices. Drop the 1.5x cap adjustment from your refund working for supplies from 1 November 2026, and take advice on claims covering earlier supplies. Clear or record pending demands; they can be adjusted against cash ledger refunds. Track the 10-day window after filing; diarise the deemed acknowledgement date. Watch for RFD-04 within 3 working days of acknowledgement. Track the 60-day final order date and interest from day 61.
How Figment's products help
Key takeaways
From 1 November 2026, refund claims must be acknowledged or flagged within 10 days, or they are deemed acknowledged. For low-risk claims, the portal generates the provisional refund order within 3 working days of acknowledgement. Provisional refund now covers inverted duty claims, not just zero-rated supplies. The 1.5x export turnover cap is gone, and small export refunds below ₹1,000 are now paid for goods exported on payment of tax. RFD-01 asks for invoice-level detail from 1 December 2026, so clean, reconciled data matters more than before.
Frequently Asked Questions
If the officer does not issue RFD-02 or RFD-03 within 10 days of filing, the refund application is treated as acknowledged under Rule 90(3A), and the portal issues the acknowledgement.
For claims the system rates as low-risk, the portal generates the provisional refund order (RFD-04) within three working days of acknowledgement. Other claims are scrutinised by the officer.
Yes. From 1 November 2026, Section 54(6), as amended by Section 155 of the Finance Act, 2026, extends the 90% provisional refund to eligible inverted duty claims.
Yes. The restriction in Rule 89(4)(C) limiting zero-rated goods turnover to 1.5 times the value of like domestic goods has been omitted from 1 November 2026. The notification does not set out separate transitional treatment for claims covering earlier supplies.
Notification No. 03/2026–Central Tax (Finance Act, 2026, Sections 153 to 155) and Notification No. 05/2026–Central Tax (CGST (Amendment) Rules, 2026), both dated 26 October 2026.