

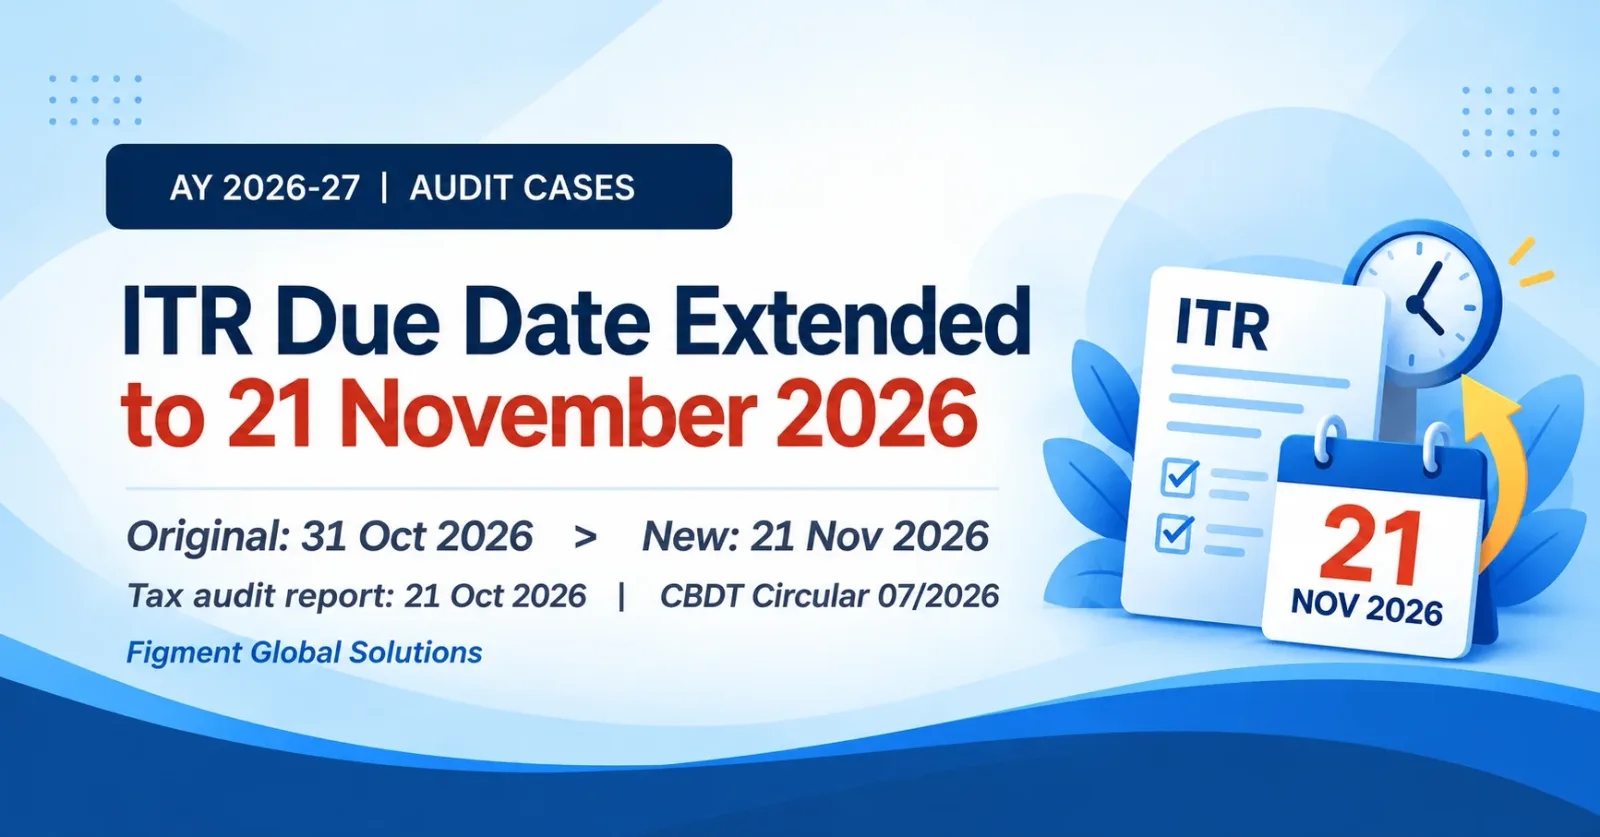
ITR Due Date 21 November 2026 for Audit Cases: CBDT Circular 07/2026 Explained
What CBDT Circular 07/2026 says
| Item | Earlier date | Extended date |
|---|---|---|
| Tax audit report under section 44AB (AY 2026-27) | 30 September 2026 | 21 October 2026 |
| Return of income for persons in sl. no. 2 of the circular's table (Explanation 2 to section 139(1)) | 31 October 2026 | 21 November 2026 |
Who gets the extended date
What the circular does not address
Interest under section 234A. The circular says nothing on interest under sections 234A, 234B or 234C. Section 234A is calculated by reference to the due date under section 139(1), and the circular does not state which date applies for interest. Until CBDT clarifies, a cautious approach is to pay the estimated self-assessment tax before filing and treat any interest from 1 November 2026 as possible exposure. Advance tax. Instalment dates and interest under sections 234B and 234C are not changed by this circular. TDS statements. The extension applies to returns of income and audit reports. It does not move TDS or TCS statement dates, so Q2 statements were still due on 31 October 2026. Belated and revised returns. The usual outer limit for a belated or revised return, 31 December of the assessment year, is unchanged.
What happens if the 21 November date is missed
| Consequence | Position under the 1961 Act |
|---|---|
| Late fee under section 234F | ₹5,000, or ₹1,000 if total income is up to ₹5 lakh |
| Interest under section 234A | 1% per month or part of a month on unpaid tax (see the note above on the start date) |
| Loss carry-forward | Most losses cannot be carried forward if the return is not filed by the due date |
| Penalty for no audit | Section 271B: 0.5% of turnover or receipts, capped at ₹1,50,000 |
Pre-filing checklist for audit-case returns
| # | Check | Why it matters |
|---|---|---|
| 1 | Audit report filed and accepted on the e-filing portal | The return cannot be filed without it for covered cases |
| 2 | UDIN generated and reported on the portal | The auditor must complete this before the report is accepted |
| 3 | Financial statements and tax audit schedules agree | Mismatches lead to revised returns |
| 4 | TDS and TCS credits compared with Form 26AS and AIS | Unclaimed or mismatched credit is the commonest refund delay |
| 5 | TDS statements filed and corrected for the year | Clause 34 of Form 3CD reports TDS compliance, and non-deduction or non-payment of TDS can lead to a 30% disallowance under section 40(a)(ia) |
| 6 | Advance tax paid and interest computed | Avoids a surprise at filing |
| 7 | Brought-forward losses and MAT/AMT credit confirmed | These need correct carry-forward schedules |
| 8 | Open notices, intimations or demands reviewed | Pending adjustments can change the tax position |
| 9 | Return verified within 30 days of filing | An unverified return is treated as not filed |
| 10 | Client sign-off recorded | Keeps a clear record of the filed position |
Reconcile credits and watch for notices
How Figment's tools help
TaxCPC: Figment's TDS return filing software. It prepares and files Forms 138 (24Q), 140 (26Q), 144 (27Q) and 143 (27EQ), validates records and PANs, matches challans against the CSI file, and supports correction returns for TRACES defaults such as short deduction, short payment and late filing. It also requests Conso files and justification reports from TRACES and shows the status of each TAN and quarter. NoticeCPC: Figment's notice management software. It tracks Income Tax, TDS, GST and AIS notices for multiple PANs, GSTINs and clients in one list, syncs from the e-filing portal and TRACES, sends alerts before response deadlines, and lets teams assign each notice to an owner. Replies to Income Tax notices are still filed on the portal.
Key takeaways
The ITR due date 21 November 2026 applies to AY 2026-27 audit cases covered by CBDT Circular 07/2026, not to all taxpayers. The tax audit report date was extended to 21 October 2026 and has now passed. Transfer pricing cases are not covered: Form 3CEB stays at 31 October and their return at 30 November 2026. The circular is silent on section 234A interest, so pay self-assessment tax before filing. TDS statement dates and advance tax dates did not move. Close TDS credit mismatches and open notices before filing, not after.
Frequently Asked Questions
21 November 2026, extended from 31 October 2026 by CBDT Circular 07/2026 dated 28 September 2026.
No. It applies to the persons at serial number 2 of the circular's table, whose normal due date was 31 October. Non-audit taxpayers (31 July) and transfer pricing cases (30 November) are not covered.
21 October 2026, extended from 30 September 2026. That date has now passed, so any pending report needs immediate attention.
The circular does not say. Until CBDT clarifies, pay estimated self-assessment tax before filing and treat interest from 1 November 2026 as possible exposure.
Yes, as a belated return up to 31 December 2026, with a late fee under section 234F, interest, and loss carry-forward restrictions.