

Quick answer
Why the codes changed
393(1): payments to residents (contractors, professionals, rent, interest, commission and so on) 393(2): payments to non-residents 393(3): payments to any person (lottery and online game winnings, cash withdrawals, payments to partners)
The most used codes at a glance
| Payment | Old section | Old challan code | New provision | New payment code | Rate |
|---|---|---|---|---|---|
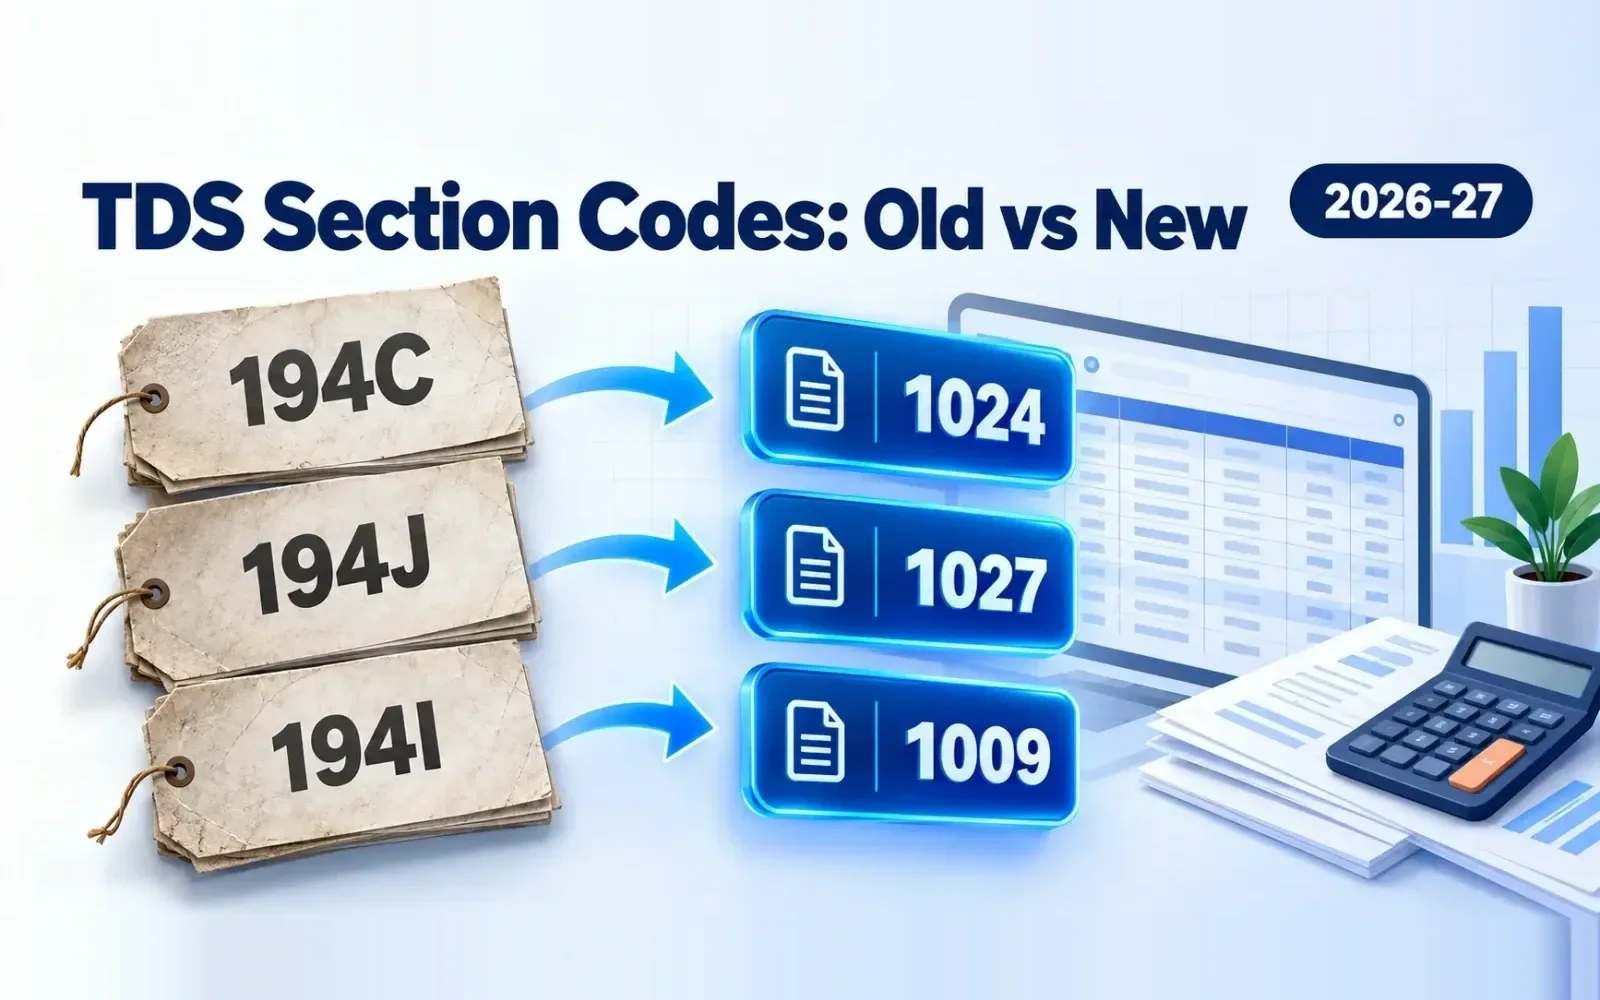
| Contractor, individual or HUF | 194C | 94C | 393(1) Sl. 6(i) | 1023 | 1% |
| Contractor, others | 194C | 94C | 393(1) Sl. 6(i) | 1024 | 2% |
| Professional fees | 194J(b) | 4JB | 393(1) Sl. 6(iii) | 1027 | 10% |
| Technical fees, call centre, film royalty | 194J(a) | 4JA | 393(1) Sl. 6(iii) | 1026 | 2% |
| Director's fees (non-salary) | 194J(b) | 4JB | 393(1) Sl. 6(iii) | 1028 | 10% |
| Rent, plant and machinery | 194I(a) | 4IA | 393(1) Sl. 2(ii) | 1008 | 2% |
| Rent, land, building, furniture | 194I(b) | 4IB | 393(1) Sl. 2(ii) | 1009 | 10% |
| Interest, bank or post office (others) | 194A | 94A | 393(1) Sl. 5(ii) | 1021 | 10% |
| Interest, other than bank | 194A | 94A | 393(1) Sl. 5(iii) | 1022 | 10% |
| Commission or brokerage | 194H | 94H | 393(1) Sl. 1(ii) | 1006 | 2% |
| Purchase of goods | 194Q | 94Q | 393(1) Sl. 8(ii) | 1031 | 0.1% |
Full mapping: payments to residents (Form 140, formerly 26Q)
| New code | Payment | Old section | New provision | Rate | Threshold |
|---|---|---|---|---|---|
| 1005 | Insurance commission (non-company 2%, company 10%) | 194D | 393(1) Sl. 1(i) | 2% / 10% | ₹20,000 |
| 1006 | Commission or brokerage | 194H | 393(1) Sl. 1(ii) | 2% | ₹20,000 |
| 1008 | Rent, plant, machinery or equipment | 194I(a) | 393(1) Sl. 2(ii) | 2% | ₹50,000 a month |
| 1009 | Rent, land, building or furniture | 194I(b) | 393(1) Sl. 2(ii) | 10% | ₹50,000 a month |
| 1011 | Joint development agreement, monetary consideration | 194IC | 393(1) Sl. 3(ii) | 10% | — |
| 1012 | Compensation on compulsory acquisition | 194LA | 393(1) Sl. 3(iii) | 10% | ₹5,00,000 |
| 1013 | Income from mutual fund units | 194K | 393(1) Sl. 4(i) | 10% | ₹10,000 |
| 1014–1016 | Business trust: interest, dividend, rent to resident unit holders | 194LBA | 393(1) Sl. 4(ii) | 10% | — |
| 1017 | Income from investment fund units | 194LBB | 393(1) Sl. 4(iii) | 10% | — |
| 1018 | Income from securitisation trust | 194LBC | 393(1) Sl. 4(iv) | 10% | — |
| 1019 | Interest on securities | 193 | 393(1) Sl. 5(i) | 10% | ₹10,000 |
| 1020 | Bank / post office interest, senior citizen | 194A | 393(1) Sl. 5(ii) | 10% | ₹1,00,000 |
| 1021 | Bank / post office interest, others | 194A | 393(1) Sl. 5(ii) | 10% | ₹50,000 |
| 1022 | Other interest | 194A | 393(1) Sl. 5(iii) | 10% | ₹10,000 |
| 1023 | Contract work, individual or HUF | 194C | 393(1) Sl. 6(i) | 1% | ₹30,000 a payment / ₹1,00,000 a year |
| 1024 | Contract work, others | 194C | 393(1) Sl. 6(i) | 2% | ₹30,000 a payment / ₹1,00,000 a year |
| 1026 | Technical fees, film royalty, call centre | 194J(a) | 393(1) Sl. 6(iii) | 2% | ₹50,000 |
| 1027 | Professional fees | 194J(b) | 393(1) Sl. 6(iii) | 10% | ₹50,000 |
| 1028 | Director's remuneration (non-salary) | 194J(b) | 393(1) Sl. 6(iii) | 10% | None |
| 1029 | Dividend | 194 | 393(1) Sl. 7 | 10% | ₹10,000 (individual) |
| 1030 | Life insurance payout (taxable part) | 194DA | 393(1) Sl. 8(i) | 2% | ₹1,00,000 |
| 1031 | Purchase of goods | 194Q | 393(1) Sl. 8(ii) | 0.1% | Above ₹50 lakh a year |
| 1033 | Business perquisite | 194R | 393(1) Sl. 8(iv) | 10% | ₹20,000 |
| 1035 | E-commerce operator | 194O | 393(1) Sl. 8(v) | 0.1% | ₹5 lakh (individual / HUF) |
| 1037 | Virtual digital asset | 194S | 393(1) Sl. 8(vi) | 1% | ₹10,000 |
| 1058 | Lottery, crossword, card game, betting | 194B | 393(3) Sl. 1 | 30% | ₹10,000 a transaction |
| 1060 | Online game winnings | 194BA | 393(3) Sl. 2 | 30% | — |
| 1062 | Horse race winnings | 194BB | 393(3) Sl. 3 | 30% | ₹10,000 a transaction |
| 1063 | Commission on lottery tickets | 194G | 393(3) Sl. 4 | 2% | ₹20,000 |
| 1064 | Cash withdrawal, co-operative society | 194N | 393(3) Sl. 5 | 2% | ₹3 crore a year |
| 1065 | Cash withdrawal, others | 194N | 393(3) Sl. 5 | 2% | ₹1 crore a year |
| 1066 | NSS withdrawal | 194EE | 393(3) Sl. 6 | 10% | ₹2,500 |
| 1067 | Salary, commission or interest to a partner | 194T | 393(3) Sl. 7 | 10% | ₹20,000 |
Payments to non-residents (Form 144, formerly 27Q)
| New code | Payment | Old section | Rate |
|---|---|---|---|
| 1039 | Non-resident sportsman, entertainer or sports association | 194E | 20% |
| 1040 / 1041 | Interest on foreign-currency borrowing / rupee bonds (before 1 July 2023) | 194LC / 194LD | 5% |
| 1042 / 1043 | Interest on IFSC-listed bonds | 194LC | 4% / 9% |
| 1044 | Interest from infrastructure debt fund | 194LB | 5% |
| 1045 / 1046 | Business trust: interest / dividend | 194LBA | 5% / 10% |
| 1050–1055 | Mutual fund, offshore fund, GDR and FII income | 196A–196D | 10%–20% |
| 1057 | Any other sum to a non-resident (fees for technical services, royalty, capital gains, others) | 195 | Rate depends on the income |
TCS codes (Form 143, formerly 27EQ)
Salary TDS
Which code to use, by period
Deducted on or after 1 April 2026: new payment codes, new forms (138, 140, 143, 144). Deducted up to 31 March 2026: old section codes and old forms (24Q, 26Q, 27Q, 27EQ), including correction statements filed today for FY 2025-26 or earlier. Late payment of old-period TDS: if you deposit TDS deducted in March 2026 after 1 April 2026, the challan should still carry the old section code for that period.
Common mistakes that create TRACES defaults
| Mistake | Result | Fix |
|---|---|---|
| Choosing 1024 (2%) for a professional fee | Short deduction of 8% | Classify by service: professional fees are 1027 |
| Using 1023 for a company contractor | Short deduction of 1% | 1023 is only for individuals and HUFs; companies and firms are 1024 |
| Booking all interest under 1022 | Wrong threshold applied | Bank and post office interest is 1020 or 1021 |
| Challan code doesn't match the return | Challan not matched, "short payment" default | Use the same payment code in the challan and the return, or correct the challan |
| Old ERP code mapped to "393" without a payment code | Return rejected or wrong nature of payment | Map every vendor and GL to the four-digit code |
Updating your ERP and vendor master
Frequently Asked Questions
1023 when the contractor is an individual or HUF (1%), and 1024 for any other contractor (2%), under section 393(1), Table Sl. No. 6(i).
1027 for professional fees (10%), 1026 for technical fees, call centres and film royalties (2%), and 1028 for director's fees other than salary (10%).
1008 for plant, machinery or equipment (2%) and 1009 for land, building or furniture (10%).
Section 393 of the Income-tax Act, 2025: sub-section (1) for residents, (2) for non-residents and (3) for payments to any person.
No. TDS deducted up to 31 March 2026 stays under the 1961 Act, so corrections for those periods use the old section codes and forms.
Yes. TCS moves from section 206C to section 394, with payment codes 1068 to 1092, reported in Form 143 (formerly 27EQ).