

When ITR-BN is used
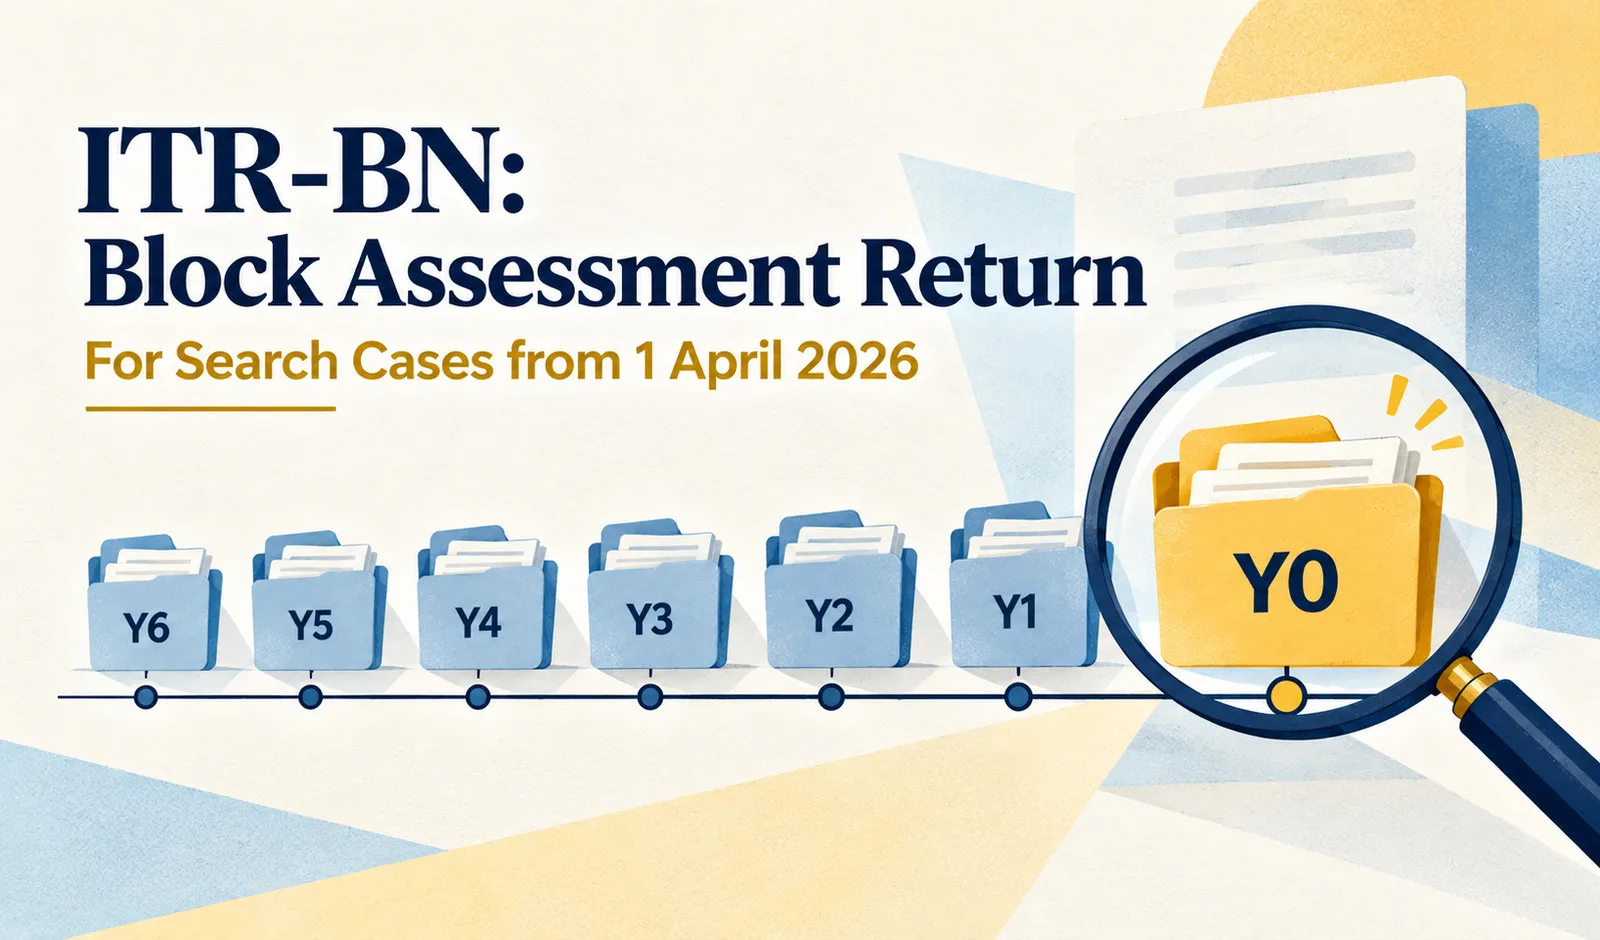
Block period covered by the form
| Period in ITR-BN | What it covers |
|---|---|
| Tax Years Y6 to Y1 | The six tax years preceding the tax year in which the search was initiated or requisition made |
| Tax Year Y0 (part year) | Where the search ends in the same year: 1 April of that year up to the execution of the last authorisation |
| Tax Year Y0 (complete year) | Where the last authorisation is executed in a later tax year: the full year of initiation |
| Tax Year Y+1 (part year) | 1 April of the year of the last authorisation up to its execution date |
What the form asks for
Part A: PAN, contact details, status, residential status, date of initiation of search or requisition, date of execution of the last authorisation, the DIN and due date of the Section 294 notice. For each tax year in the block: date and section of the last return filed (under the 1961 Act or the 2025 Act) and whether any assessment or reassessment was pending on the search date. Aggregate value of international and specified domestic transactions (Form 3CEB under the 1962 Rules or Form 48 under the 2026 Rules, or provisional values). Part C: year-wise computation of undisclosed income, separating income already disclosed or assessed before the search. Part D: head-wise and item-wise break-up of undisclosed income, including money, bullion, jewellery, virtual digital assets, expenditure and incorrect claims of expense, exemption, deduction or allowance. Parts F to H: self-assessment tax paid and credit claimed for advance tax, self-assessment tax and TDS/TCS not claimed earlier.
Tax payable in ITR-BN
| Component | Rate or basis |
|---|---|
| Tax on undisclosed income of the block period | 60% of the undisclosed income declared |
| Surcharge | On the tax above, if applicable |
| Health and Education Cess | 4% on tax plus surcharge |
| Interest | Under Section 298(1) of the Income-tax Act, 2025 |
Points practitioners should note
Undisclosed income relating to international or specified domestic transactions for the part tax year is assessed outside the block assessment provisions (Section 293(5)) and is not included in ITR-BN. For a year whose return due date had not expired on the search date, provisional figures from the books are reported; this is not treated as the regular return, and the income must still be included in the regular return for that year. References to tax years beginning on or before 1 April 2025 are read as the corresponding previous years under the Income-tax Act, 1961. The notification states that no person is adversely affected by the retrospective effect from 1 April 2026.
Applies to searches from 1 April 2026
Frequently Asked Questions
ITR-BN is the income tax return for block assessment in search and seizure cases under Chapter XVI-B of the Income-tax Act, 2025, inserted as Appendix IV to the Income-tax Rules, 2026 by Notification No. 97/2026.
The rules are deemed to be in force from 1 April 2026 and apply to searches initiated under Section 247 or requisitions made under Section 248 on or after that date.
60% of the undisclosed income of the block period, plus surcharge if applicable, 4% Health and Education Cess, and interest under Section 298(1).
The six tax years before the year of search, plus the year of search up to the execution of the last authorisation (and part of the next year where the last authorisation is executed in a later year).
Undisclosed income relating to international or specified domestic transactions for the part tax year is assessed outside the block provisions under Section 293(5), so it is not included in ITR-BN.