

The problem Rule 14B solves
Eligibility at a glance
| Condition | Requirement |
|---|---|
Step-by-step: applying under Rule 14B
Start a new registration
On the GST portal, go to Services → Registration → New Registration and start FORM GST REG-01. Choose the Rule 14B option
In Part B, Business Details tab, select "Yes" for "Option for Registration under Rule 14B" and accept the declaration. Enter your home State GSTIN
It must be regular, active and under the same PAN. The reason for registration is auto-filled as "Selling through e-Commerce portal". Request the ECO's warehouse address
In the PPoB/APoB tab, enter the ECO's GSTIN in that State. This sends an address access request to the operator. Get the operator's consent
The ECO approves the warehouse address(es) within 7 working days and gives the details of its authorised representative in that State. Without consent, no ARN is generated. Select the warehouse as PPoB
Select the approved warehouse address as PPoB and, if needed, other warehouses as additional places of business. The nature of possession is auto-filled as "E-Commerce Operator's Warehouse under Rule 14B". Complete Aadhaar authentication
Complete biometric Aadhaar authentication at a GST Suvidha Kendra if not already done for the home GSTIN. The advisory says this must be completed within 15 days of submitting Part B for the ARN to be generated. Verification and approval
The home State PPoB may be physically verified. The application is deemed approved after a successful field visit or 30 days from the ARN, whichever is earlier, and the certificate is issued electronically.
Obligations after registration
Books of account are kept at the home State PPoB and must be produced on demand. No display requirement at the warehouse: the registration certificate and GSTIN name board need not be displayed at the ECO's premises. Returns: there is no separate or simplified return. The Rule 14B GSTIN is a regular registration and files GSTR-1, GSTR-3B and, where applicable, GSTR-9. Stock transfers from the home State to the warehouse are inter-State supplies between distinct persons, so IGST, e-way bills and (where applicable) e-invoices apply as usual. The ₹2.5 lakh cap must be monitored every month. Exceeding it is a listed reason for withdrawing from Rule 14B in FORM GST REG-32: the seller applies to withdraw, gives an address showing physical presence in that State and goes through verification, after which the withdrawal order is issued in REG-33. Crossing the limit is not listed as a ground for automatic cancellation.
Exit and deemed cancellation
| Event | What happens |
|---|---|
Rule 14A vs Rule 14B
| Point | Rule 14A (from 1 Nov 2025) | Rule 14B (from 1 Nov 2026) |
|---|---|---|
Compliance checklist for sellers
Confirm your home State GSTIN is regular, active, not under Rule 14A or Rule 9A, and has no cancellation pending. Check your B2B output tax per month is within ₹2.5 lakh. Confirm the ECO collects TCS under Section 52 and is ready to give consent. Keep the promoter and primary authorised signatory available for biometric Aadhaar authentication. Make sure the home State address will pass a physical verification. Set up IGST stock transfer invoices and e-way bills from the home State. Track monthly returns and TCS credits for each new GSTIN. Diarise the 30-day window to amend PPoB if the ECO withdraws consent.
How Figment's products help
Key takeaways
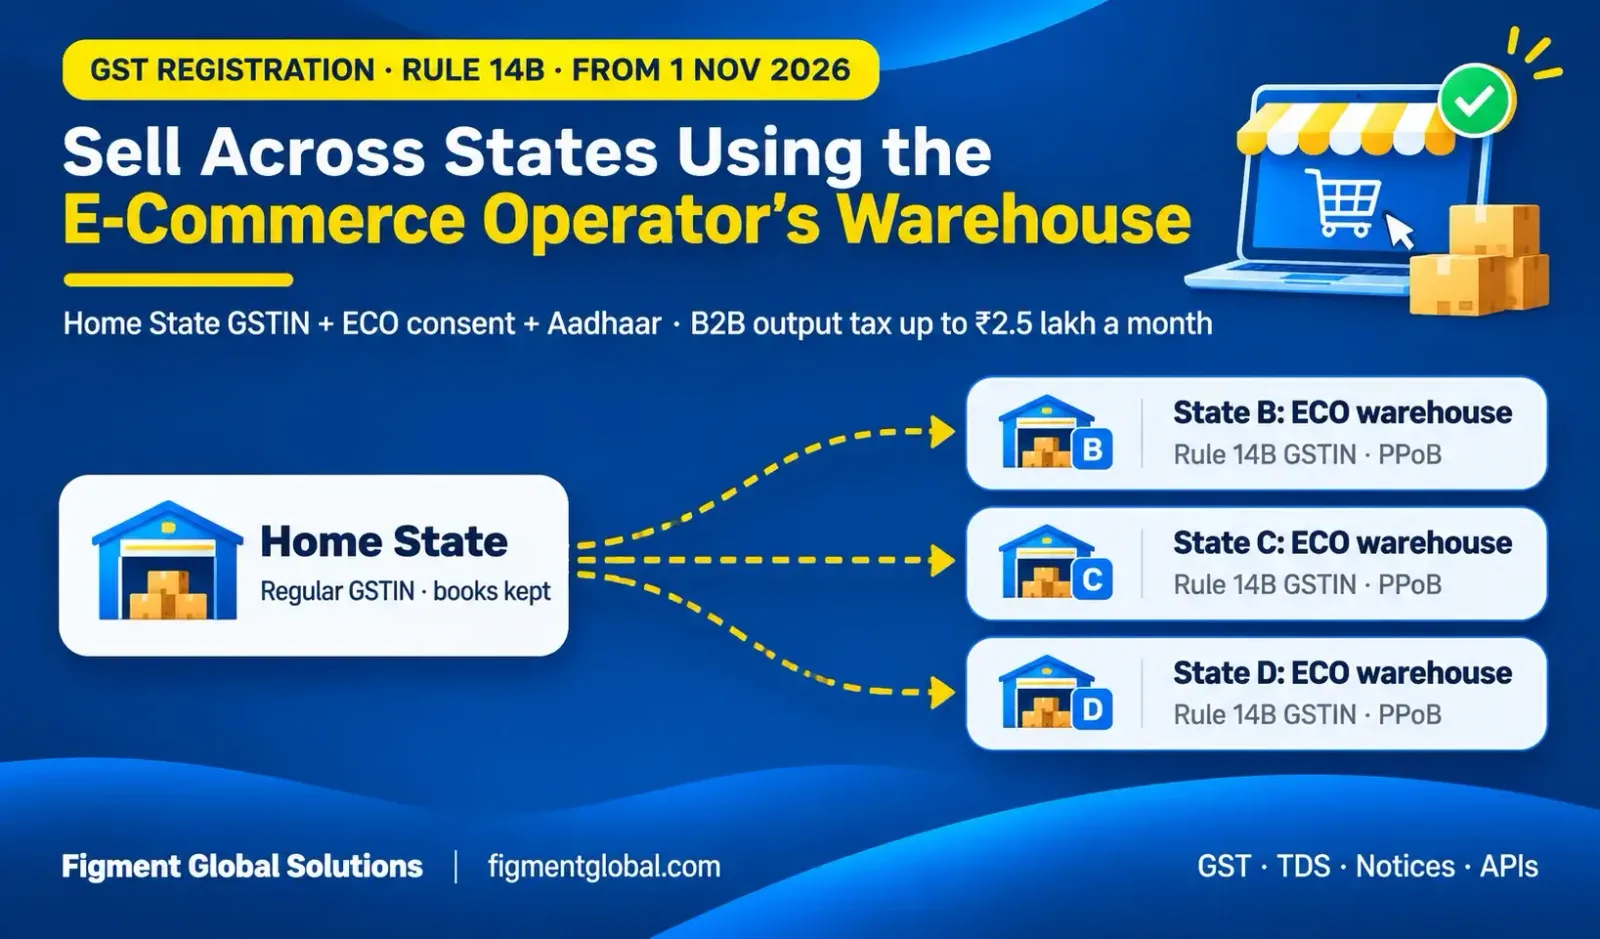
From 1 November 2026, Rule 14B lets e-commerce sellers register in other States using the ECO's warehouse as PPoB. The seller needs a regular home State registration and must keep B2B output tax within ₹2.5 lakh per month. The ECO must consent within 7 working days; Aadhaar authentication and home State verification follow. Approval is deemed after 30 days from ARN if the field visit is not done. The registration can be used only for supplies through ECOs, and lapses if the operator withdraws and the seller does not amend within 30 days.
Frequently Asked Questions
A rule inserted by Notification 05/2026–Central Tax, effective 1 November 2026, that lets a seller register in another State by declaring an e-commerce operator's warehouse as its principal place of business.
A seller with an active regular registration in its home State, selling goods through Section 52 ECOs, with no physical presence in the target State, and with output tax on B2B supplies of not more than ₹2.5 lakh a month.
No. As per the GSTN advisory, the registration must be used only for supplies made through e-commerce operators.
After ECO consent and Aadhaar authentication, the application is deemed approved after a successful field visit or 30 days from the ARN, whichever is earlier.
You must amend your principal place of business in REG-14 within 30 days. Otherwise, the registration is deemed cancelled.