

Quick answer:
1. New TDS and TCS form numbers
| What it is | Old form (1962 Rules) | New form (2026 Rules) |
|---|---|---|
| Quarterly statement: salary | 24Q | 138 |
| Quarterly statement: payments to residents | 26Q | 140 |
| Quarterly statement: TCS | 27EQ | 143 |
| Quarterly statement: payments to non-residents | 27Q | 144 |
| Challan-cum-statement (property, rent, contracts, VDA) | 26QB / 26QC / 26QD / 26QE | 141 (single form) |
| Statement by Government offices (PAO) | 24G | 137 |
| TDS certificate: salary | 16 | 130 |
| TDS certificate: non-salary | 16A | 131 |
| Certificates for challan-cum-statements | 16B / 16C / 16D / 16E | 132 |
| TCS certificate | 27D | 133 |
| Lower / nil deduction certificate application | 13 | 128 |
| Self-declaration for no TDS | 15G and 15H | 121 (single form) |
| Foreign remittance forms | 15CA / 15CB | 145 / 146 |
| Annual tax statement | 26AS / AIS | 168 |
| TAN application | 49B | 134 (Government) / 135 (others) |
2. Section codes: quote the table entry, not 194-series
On or before 31 March 2026: Income-tax Act, 1961. On or after 1 April 2026: Income-tax Act, 2025. For salary, the date of payment decides.
3. What is new on TRACES
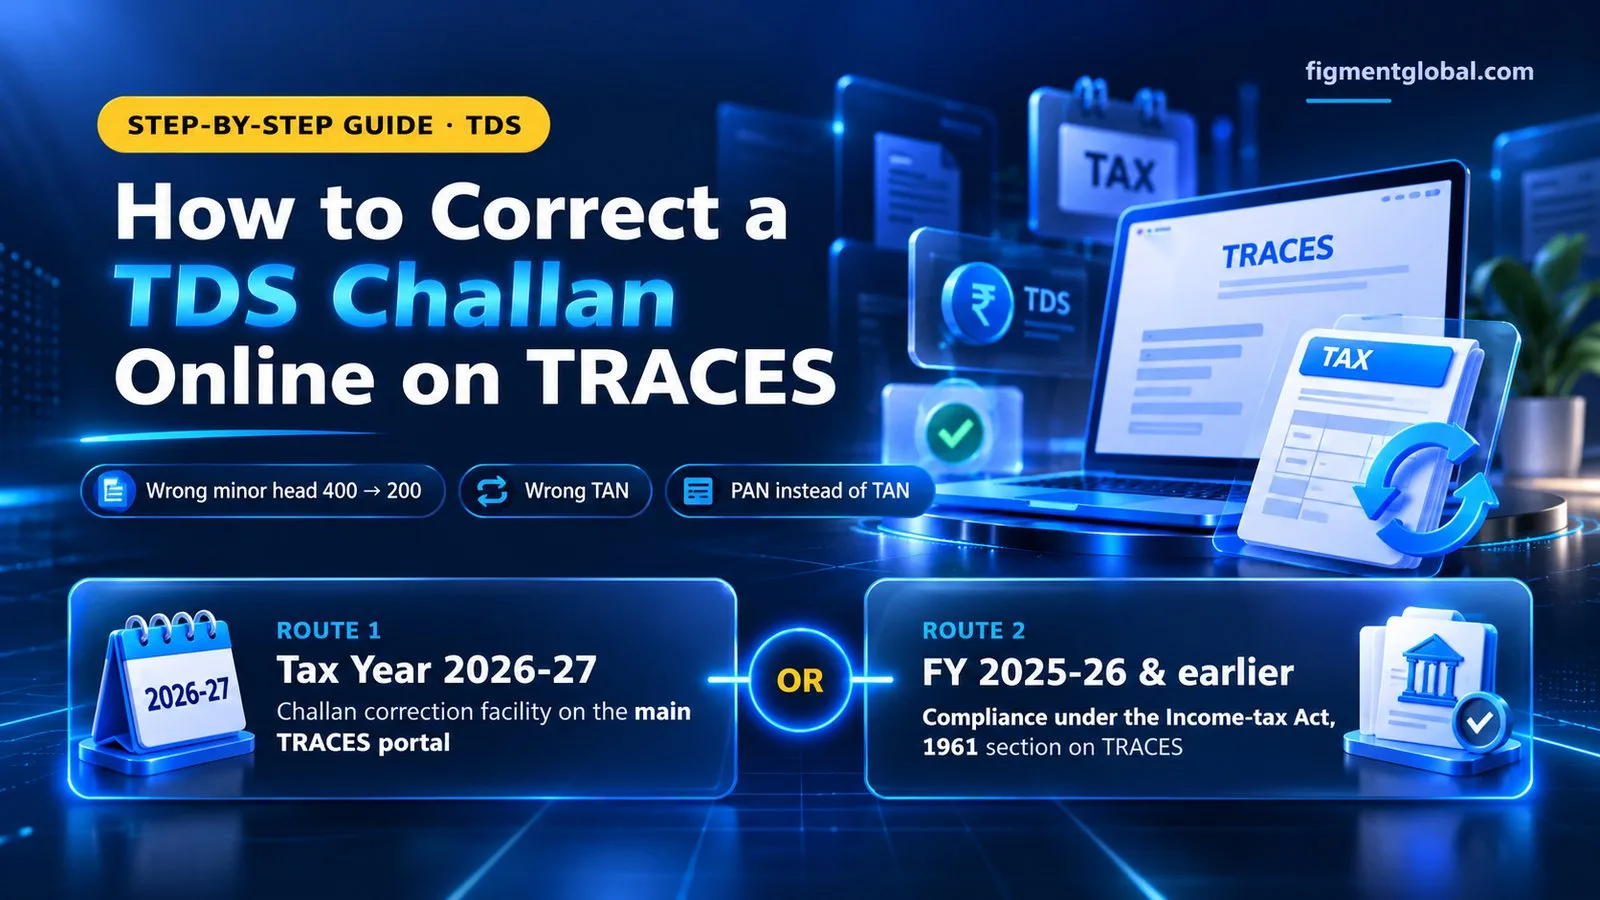
Online filing of TDS/TCS statements. Original and correction statements in Forms 138, 140, 143 and 144 can be prepared, validated and filed on the TRACES portal, without an offline utility. Online filing of original statements for Q2 of tax year 2026-27 is enabled. Offline route still available. CBDT's Form 140 guidance still describes preparing the statement with RPU, validating it with FVU and uploading it, so online filing on TRACES is an additional option, not the only one. Update your profile first. TRACES asks deductors to update mobile number, email, address and PAN-Aadhaar linking in the profile before filing online. Challan correction is available for tax year 2026-27. Corrections for FY 2025-26 and earlier go through the "Compliance under the Income-tax Act, 1961" menu. See our step-by-step guide to TDS challan correction on TRACES. Form 141 corrections are available for Schedules A, B, C and D (cash). Schedule D (kind) is listed as coming shortly. Downloads for tax year 2026-27: TDS certificates, default summaries, justification reports, Conso files and PAN error reports. Bulk certificate generation: deductors having trouble generating large numbers of certificates are asked to install the latest utility, version 2.1 Beta. New Conso file formats under the Income-tax Act, 2025: one for Form 138 and one for Forms 140, 143 and 144. Update any in-house parsers that read Conso files. Form 26A requests for FY 2025-26 and earlier PAN-based statements (26QB/26QC/26QD/26QE) are available under the 1961 Act compliance menu. Form 137 (old 24G) filing for PAOs is listed as coming shortly, through TRACES only. DIN verification is enabled for tax year 2026-27. Fraud warning: CPC-TDS says genuine communications come only from the @tdscpc.gov.in domain.
4. RPU and FVU versions
| Period | Return Preparation Utility | File Validation Utility |
|---|---|---|
| Tax year 2026-27 onwards | RPU 1.2 | FVU 1.2 |
| Up to FY 2025-26 | RPU 6.0 | FVU 9.5 (FY 2010-11 to FY 2025-26) |
| Up to FY 2009-10 | — | FVU 2.191 |
5. Due dates for tax year 2026-27
Quarterly TDS/TCS statements (Forms 138, 140, 143 and 144)
| Quarter | Period | Due date |
|---|---|---|
| Q1 | April–June 2026 | 31 July 2026 |
| Q2 | July–September 2026 | 31 October 2026 |
| Q3 | October–December 2026 | 31 January 2027 |
| Q4 | January–March 2027 | 31 May 2027 |
Certificates
| Certificate | Due date |
|---|---|
| Form 130 (salary) | 15 June after the tax year (15 June 2027 for tax year 2026-27) |
| Form 131 (non-salary) and Form 133 (TCS) | 15 August, 15 November, 15 February and 15 June |
| Form 132 | Within 15 days of the due date of the challan-cum-statement |
Correction window:
6. Interest, late fee and disallowance
| Consequence | 1961 Act | 2025 Act | Amount |
|---|---|---|---|
| Interest for failure to deduct | 201(1A) | 398(3)(a) | 1% a month |
| Interest for failure to deposit after deduction | 201(1A) | 398(3)(a) | 1.5% a month |
| Late fee for delayed statement | 234E | 427 | ₹200 a day, capped at the TDS/TCS amount; must be paid before the statement is filed |
| Disallowance of expense for TDS default | 40(a)(ia) | 35(b) | 30% of the sum |
7. Lower deduction certificates: Form 13 is now Form 128
New applications are made in Form 128, online on TRACES only. Certificates applied for and issued by 31 March 2026 are protected under section 536. Applications pending on 1 April 2026 for tax year 2026-27 are treated as filed under the 2025 Act; applications made from 1 April 2026 are dealt with entirely under it. An old section 197 certificate issued for projected tax year 2026-27 receipts stays valid for payments on or after 1 April 2026. TRACES is issuing tax year 2026-27 certificates under the 2025 Act for Form 13 applications filed up to 31 March 2026. Where one old section (such as 194A or 194J(b)) corresponds to several new entries, the certificate is mapped to all of them.
8. CBDT circulars in 2026 that affect TDS teams
Circular No. 2/2026: extended the due date for issuing TDS certificates for the quarter ending 31 December 2025 to 31 March 2026, because of e-filing portal issues. Circular No. 7/2026 (28 September 2026): extended the tax audit report due date for AY 2026-27 to 21 October 2026 and the return due date for audit cases to 21 November 2026. Not a TDS circular, but it shifts year-end reconciliation work for many deductors.
9. Old-period work after 1 April 2026
Corrections for Q1 to Q4 of FY 2025-26 and earlier are filed under the 1961 Act, in the old forms and formats. RPU and TRACES support both formats. Form 16 for FY 2025-26 and Form 16A for Q4 of FY 2025-26 were due on 15 June 2026. A late Form 16A for FY 2025-26 attracts penalty under old section 272A(2)(g). Refund of excess TDS deducted under the old Act is claimed in old Form 26B. AIS continues up to AY 2026-27. From tax year 2026-27 it is replaced by Form 168.
Checklist before you file Q2 (due 31 October 2026)
TRACES profile updated: mobile, email, address, PAN-Aadhaar link Section codes in the ERP mapped to section 392/393/394 table entries RPU 1.2 and FVU 1.2 installed, or online filing on TRACES chosen Q1 justification report and default summary downloaded and cleared Challans verified and corrected where needed before filing Form 128 certificates mapped to the right deductee PANs and table entries Form 121 declarations collected for nil-deduction cases Conso file parsers updated to the new formats
How Figment helps
Frequently Asked Questions
Form 140 under the Income-tax Rules, 2026, for payments made from 1 April 2026. 24Q is Form 138, 27Q is Form 144 and 27EQ is Form 143.
31 October 2026 for Forms 138, 140, 143 and 144.
Yes. TRACES now supports online preparation, validation and filing of original and correction statements in Forms 138, 140, 143 and 144. The RPU and FVU route also remains available.
RPU 1.2 and FVU 1.2 for tax year 2026-27 onwards; RPU 6.0 and FVU 9.5 for FY 2010-11 to FY 2025-26.
Form 130 (salary) and Form 131 (non-salary). Form 16 is still used for FY 2025-26.
₹200 per day under section 427 (old section 234E), capped at the amount of tax deductible or collectible.
File the correction under the Income-tax Act, 1961, using the old form (24Q, 26Q, 27Q or 27EQ), RPU 6.0 and FVU 9.5, or through the "Compliance under the Income-tax Act, 1961" menu on TRACES where applicable.