

What GST compliance covers
Reporting outward supplies in GSTR-1 (or IFF under QRMP). Claiming eligible ITC after matching purchases with GSTR-2B and acting on invoices in the Invoice Management System (IMS). Paying tax and filing the summary return, GSTR-3B. Transaction documents: e-invoices and e-way bills where they apply. Annual returns: GSTR-9 and, above the turnover limit, GSTR-9C.
Monthly GST compliance list
| Return / task | Who | Due date |
|---|---|---|
| GSTR-7 (TDS under GST) | Government departments and notified deductors | 10th of next month |
| GSTR-8 (TCS) | E-commerce operators | 10th of next month |
| GSTR-1 | Monthly filers | 11th of next month |
| GSTR-6 | Input Service Distributors | 13th of next month |
| IFF (optional) | QRMP taxpayers, months 1 and 2 of the quarter | 13th of next month |
| GSTR-2B available | All regular taxpayers | Generated on the 14th |
| GSTR-3B | Monthly filers | 20th of next month |
| PMT-06 tax payment | QRMP taxpayers, months 1 and 2 of the quarter | 25th of next month |
Quarterly GST compliance list
| Return | Who | Due date |
|---|---|---|
| GSTR-1 (quarterly) | QRMP taxpayers (aggregate turnover up to ₹5 crore who opted in) | 13th of the month after the quarter |
| GSTR-3B (quarterly) | QRMP taxpayers | 22nd or 24th of the month after the quarter, depending on the state |
| CMP-08 | Composition taxpayers | 18th of the month after the quarter |
Annual and half-yearly GST compliance
| Return / task | Who | Due date |
|---|---|---|
| ITC-04 (job work) | Turnover above ₹5 crore: half-yearly | 25 October and 25 April |
| ITC-04 (job work) | Turnover up to ₹5 crore: annual | 25 April |
| GSTR-4 | Composition taxpayers | 30 April after the year |
| LUT renewal (RFD-11) | Exporters supplying without paying IGST | Before the first export of the new year |
| ITC cut-off for the previous year | All regular taxpayers | 30 November, or the GSTR-9 filing date if earlier |
| GSTR-9 | Turnover above ₹2 crore (optional up to ₹2 crore) | 31 December after the year |
| GSTR-9C | Turnover above ₹5 crore (self-certified) | 31 December after the year |
Rules that changed how GST compliance works
GSTR-3B is locked for values from GSTR-1
Returns are time-barred after three years
IMS sits between your suppliers and GSTR-2B
E-invoices have a 30-day reporting limit
Return changes recommended by the 57th GST Council
ITC rules to check every month
GSTR-2B match: claim ITC only on invoices that appear in GSTR-2B and match your purchase register. Section 17(5): reverse blocked credits such as motor vehicles (with exceptions), food and beverages, and goods for personal use. Rule 37: if you have not paid a supplier within 180 days of the invoice date, reverse the ITC and reclaim it when you pay. Rule 37A: if a supplier has not filed GSTR-3B for the period by 30 September of the following year, reverse the ITC by 30 November; reclaim it once the supplier files. Supplier status: check that suppliers' GSTINs are active before you rely on their invoices. The GST verification API checks registrations in bulk.
RCM: the item most often missed
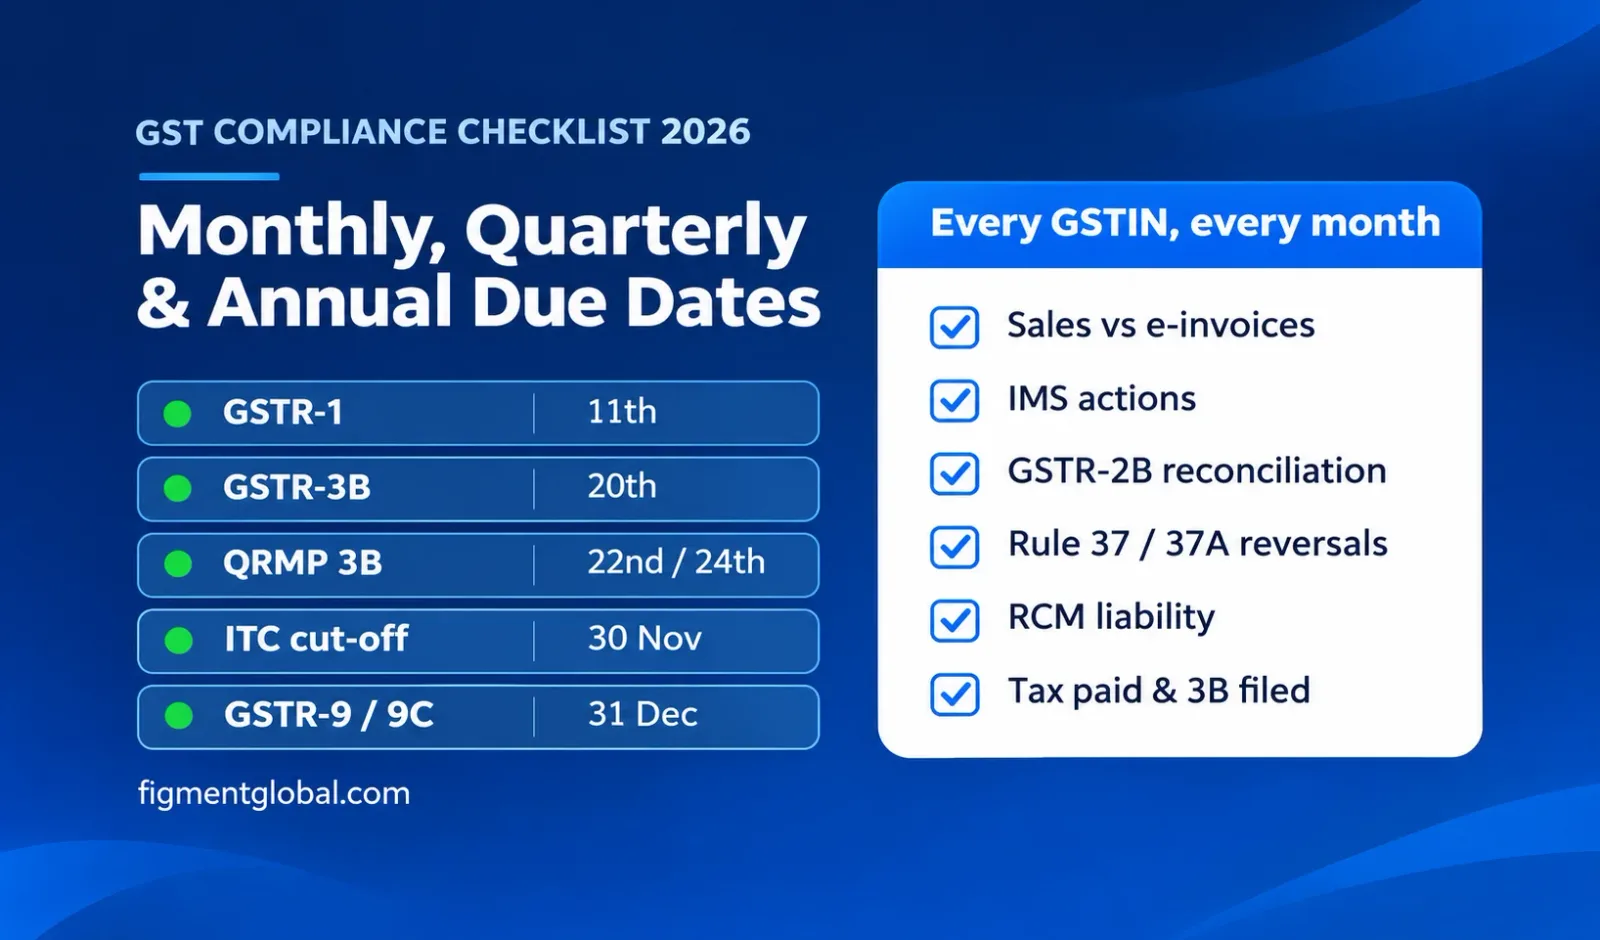
GSTIN-level monthly GST compliance checklist
| # | Check | Done before |
|---|---|---|
| 1 | Sales register reconciled with e-invoices and e-way bills | GSTR-1 (11th) |
| 2 | Credit notes, debit notes and amendments captured | GSTR-1 (11th) |
| 3 | GSTR-1 reviewed and approved, then filed | 11th |
| 4 | IMS actions taken: accept, reject or pending for each supplier invoice | GSTR-2B (14th) |
| 5 | Purchase register reconciled with GSTR-2B at invoice level | GSTR-3B |
| 6 | Blocked credits, Rule 37 and Rule 37A reversals and reclaims recorded | GSTR-3B |
| 7 | RCM liability computed and self-invoices issued | GSTR-3B |
| 8 | Cash and credit ledger balances checked; tax paid | 20th |
| 9 | GSTR-3B reviewed, approved and filed | 20th (22nd/24th for QRMP) |
| 10 | Mismatch report and vendor follow-ups sent for missing invoices | Month-end |
| 11 | Notices on the GST portal checked for every GSTIN | Weekly |
| 12 | Old unfiled returns checked against the three-year time bar | Quarterly |
How GSTCPC handles GST compliance
Return filing for GSTR-1, GSTR-1A, GSTR-3B, GSTR-9 and GSTR-9C, plus GSTR-6, GSTR-7 and ITC-04, with role-based filing controls so returns are reviewed before they are filed. GSTR-2A and GSTR-2B reconciliation against the purchase register, with ITC tracking and ITC mismatch reports. IMS actions (accept, reject and pending) on supplier invoices. A temporary ITC reversal and reclaim ledger for Rule 37 and Rule 37A movements. Multiple GSTINs under one organisation, with bulk GSTIN validation. E-invoice and e-way bill generation from the same records.
Key takeaways
GST compliance is a monthly cycle per GSTIN: GSTR-1, IMS and GSTR-2B, ITC checks, GSTR-3B, then the annual return. GSTR-3B Table 3 is now locked to GSTR-1, so fix sales data before the 11th. Returns cannot be filed more than three years after the due date. For FY 2025-26, claim ITC by 30 November 2026 and file GSTR-9/9C by 31 December 2026. Keep RCM, Rule 37 and Rule 37A in the monthly checklist, not the year-end one.
Frequently Asked Questions
Filing GSTR-1 and GSTR-3B on time, reconciling purchases with GSTR-2B and IMS before claiming ITC, paying tax including RCM, issuing e-invoices and e-way bills where required, and filing GSTR-9 and GSTR-9C each year.
GSTR-1 by the 11th and GSTR-3B by the 20th of the next month for monthly filers. GSTR-7 and GSTR-8 are due on the 10th, and GSTR-6 on the 13th.
The 22nd or 24th of the month after the quarter, depending on the state. Quarterly GSTR-1 is due on the 13th, and tax for the first two months is paid through PMT-06 by the 25th.
Not for the outward-supply values auto-filled in Table 3 from the July 2025 period onwards. Correct them through GSTR-1A before filing GSTR-3B.
No. It is optional for taxpayers with aggregate turnover up to ₹2 crore. GSTR-9C is required only above ₹5 crore and is self-certified.